BUSINESS PROTECTION
Protect the Business, People, and Plans That Depend on You
Your business may support your family, employees, partners, and long-term financial goals. An unexpected death can affect much more than one person—it can also create financial and operational challenges for the business.
PFG helps business owners review their existing protection, financial obligations, ownership concerns, and the people the business depends on before exploring appropriate life insurance strategies.
IIndependent guidance • Multiple-company access • No-pressure conversation
Insurance products are subject to eligibility and underwriting. Product features and availability vary by insurer, product, and state. Information provided is educational and is not individualized legal or tax advice.
PROTECT THE PEOPLE AND OBLIGATIONS BEHIND THE BUSINESS
Protect What Keeps Your Business Moving
Many businesses depend heavily on an owner, partner, or small group of key people. If one of them dies unexpectedly, the impact can reach revenue, payroll, debt, customer relationships, ownership plans, and the owner’s family.
Life insurance may be used to help create liquidity for needs such as the loss of a key person, business debt, ownership transition, or a properly structured buy-sell arrangement.
Before discussing a strategy, PFG looks at how the business operates, who is essential, what financial obligations exist, and what the owners want to protect.
Key Person Protection
Coverage can help provide funds to address the financial impact of losing an owner or employee whose leadership, skills, or relationships are important to the business.
Ownership & Buy-Sell Planning
Life insurance may help provide funding for an ownership transfer under a properly structured buy-sell agreement, helping the business and the owner’s family prepare for a transition.
Debt & Business Continuity
Coverage may help provide liquidity for business debts, operating needs, and other financial obligations while the business adjusts after the loss of an owner or key person.
BUSINESS PROTECTION, EXPLAINED SIMPLY
Create Financial Options for Business Continuity
A business can be financially tied to the people who lead it, generate revenue, maintain important relationships, or share ownership. When one of those people dies unexpectedly, the business may need time and money to adjust.
Life insurance can help create liquidity for specific business needs. Depending on how coverage is structured, funds may help address the loss of a key person, business debt, operating expenses, or an ownership transition.
For businesses with multiple owners, life insurance may also be used as part of a properly structured buy-sell arrangement to help provide funding if an owner dies.
PFG helps business owners understand the purpose of the coverage, who should own it, who receives the benefit, how much protection may be appropriate, and how different insurance options may fit the business.
Important to Know
Business life insurance strategies should be coordinated with the company’s ownership structure, agreements, and financial objectives. Policy ownership, beneficiaries, funding arrangements, and tax treatment can vary depending on how coverage is structured.
Insurance products are subject to eligibility and underwriting, and features vary by insurer, product, and state. PFG provides insurance guidance and educational information; business owners should work with qualified legal and tax professionals when establishing or updating business agreements.
WHAT WE REVIEW TOGETHER
A Clearer Look at Your Business Protection Needs
Every business is different. We look at the people the business depends on, ownership arrangements, financial obligations, and continuity goals before discussing what insurance strategies may be appropriate.
Key People
We identify owners, employees, or other individuals whose loss could have a meaningful financial or operational impact on the business.
Ownership & Succession
We discuss ownership structure, transition goals, and whether funding may be needed for a properly structured buy-sell arrangement.
Business Obligations
We review debts, operating expenses, payroll needs, and other financial responsibilities that could become harder to manage after an unexpected loss.
Existing Coverage & Priorities
We look at insurance already in place, your budget, and the business priorities you want to protect before comparing possible solutions.
A SIMPLE, PERSONAL PROCESS
A Clear Process for Protecting Your Business
We start by understanding how your business operates, who it depends on, the financial obligations involved, and what you want to protect. Then we help you review appropriate insurance strategies clearly.
1
Understand Your Business
We review your ownership structure, key people, existing coverage, financial obligations, and the areas of the business that could be affected by an unexpected loss.
2
Identify the Financial Impact
We look at how the loss of an owner or key person could affect revenue, debt, operating expenses, ownership plans, and business continuity.
3
Compare Appropriate Strategies
We explain available life insurance options, benefit amounts, ownership and beneficiary considerations, underwriting, and other important tradeoffs.
4
Make an Informed Decision
You decide what fits your business and priorities. Our role is to answer questions and provide clear guidance—not pressure you into a particular solution.
A straightforward conversation to understand your business protection needs and review appropriate insurance strategies.
PERSONAL GUIDANCE
Work With People Who Take the Time to Understand Your Business Needs
Business protection decisions are personal because every company is built differently. We begin by understanding your ownership structure, key people, financial obligations, existing coverage, and the goals you have for the business.
As an independent life insurance brokerage, PFG can help you review appropriate business protection strategies from multiple companies while helping you understand how the coverage may fit with your broader business plans.
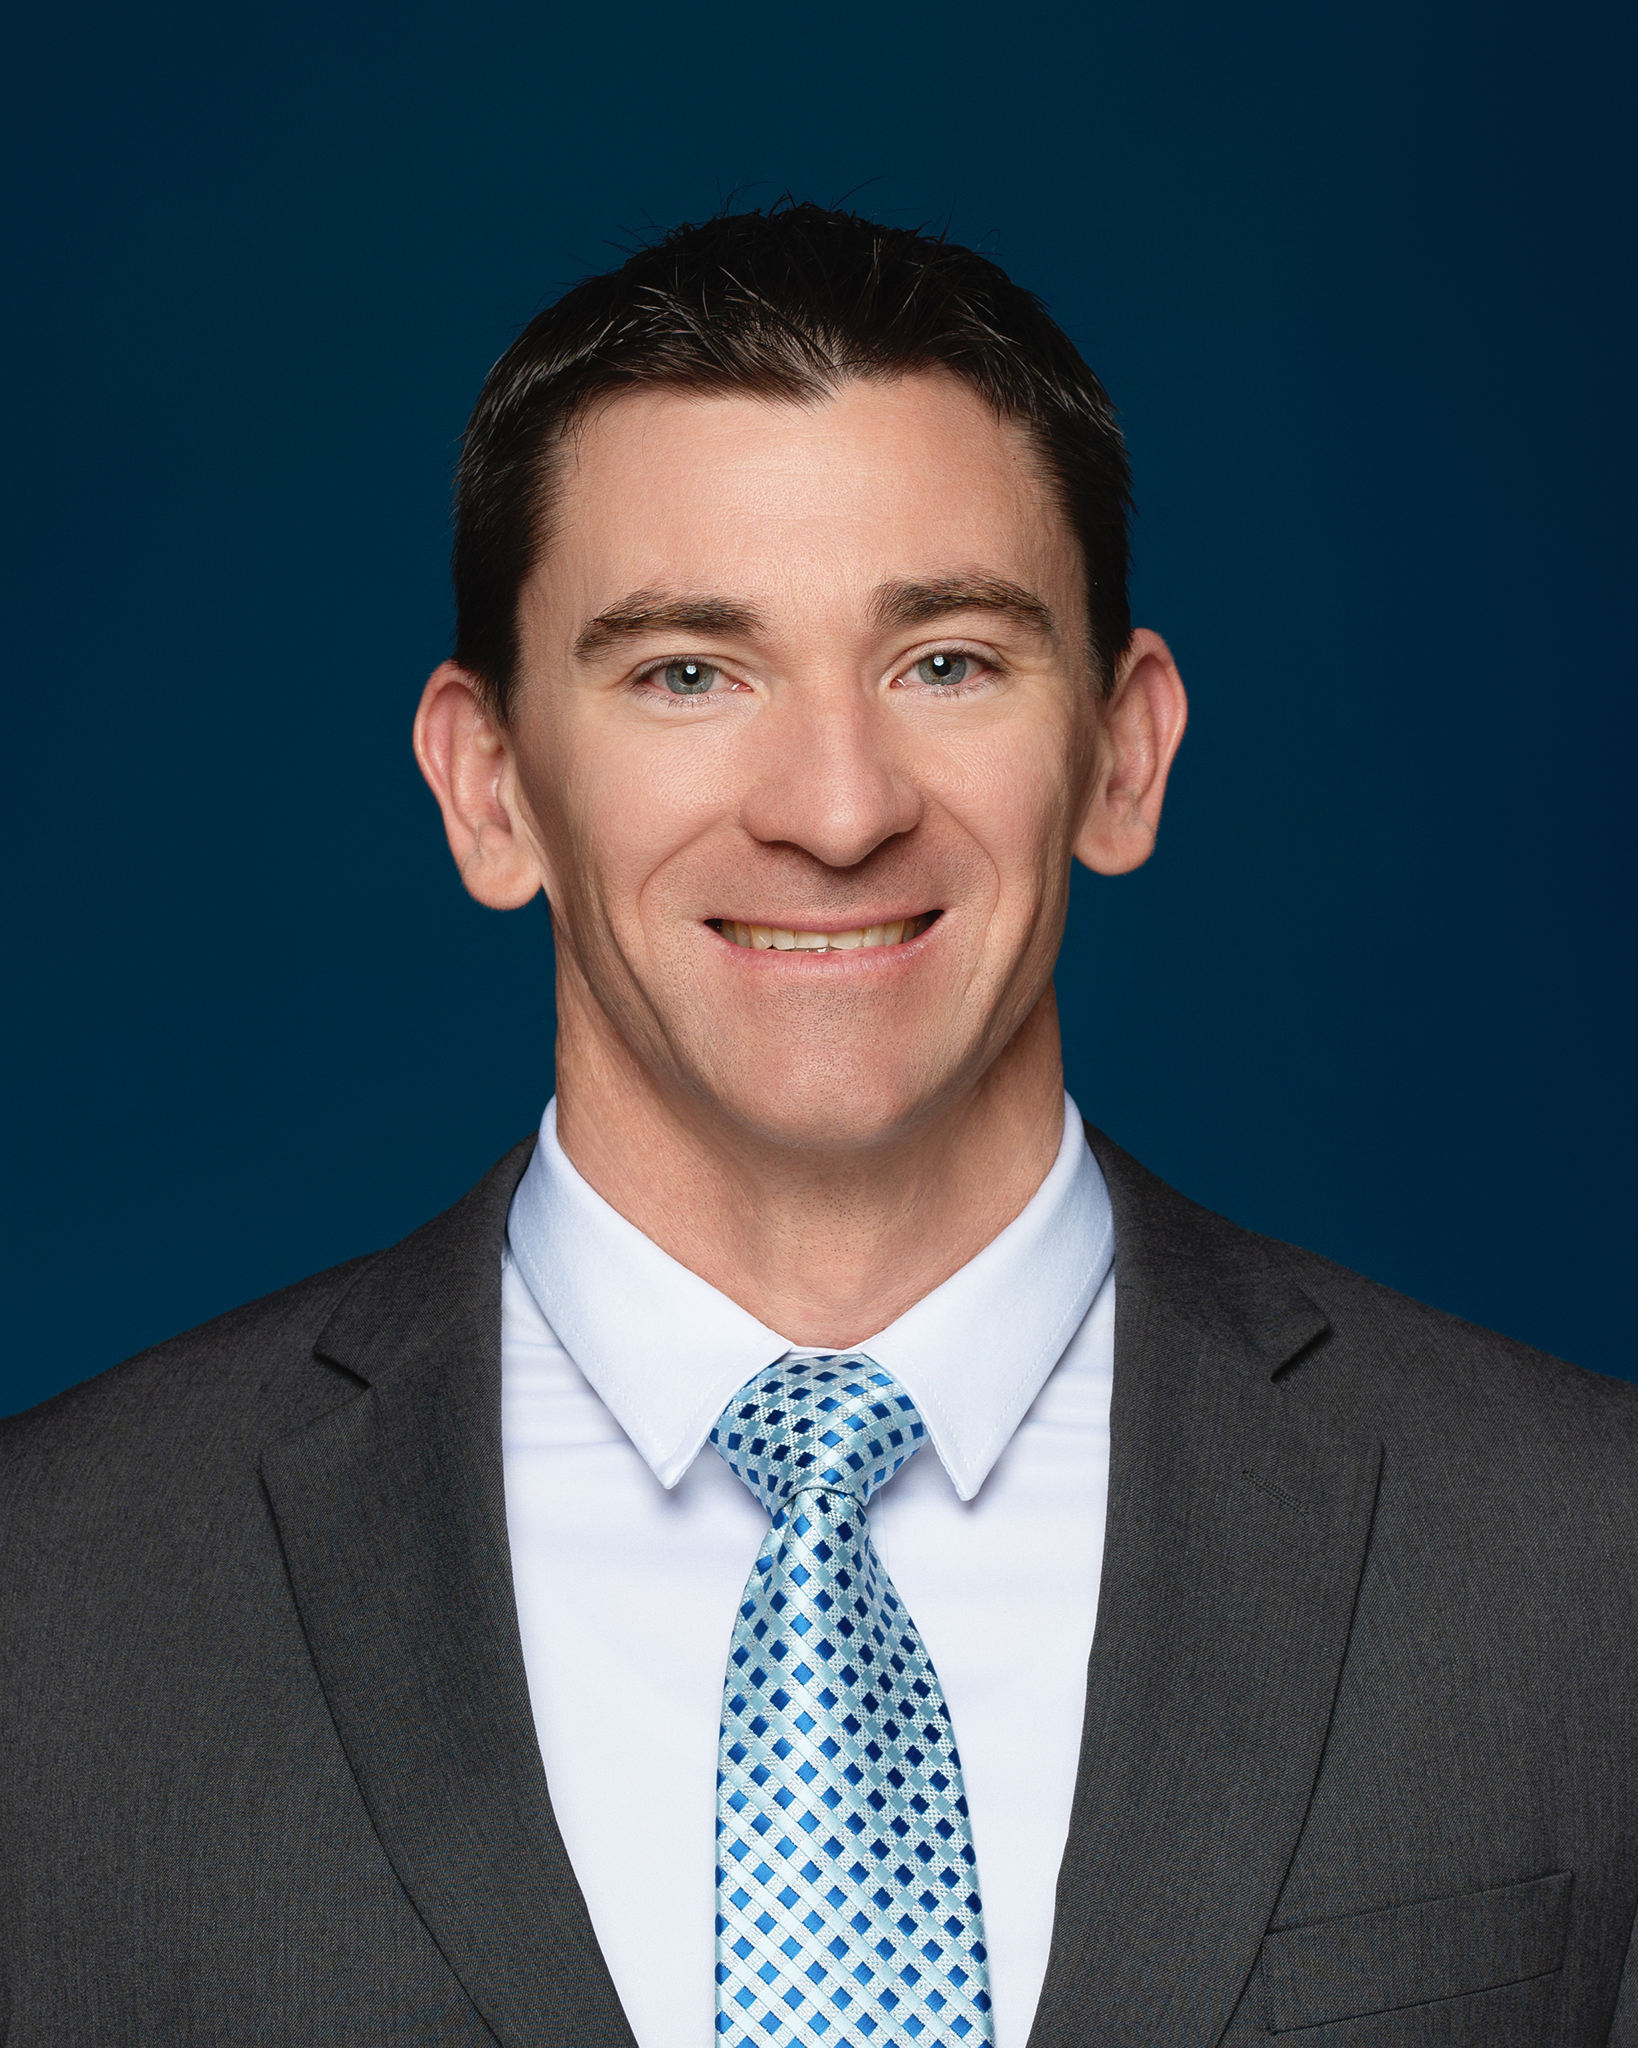
G. Aaron Coleman
Founder, Productive Financial Group
Aaron brings more than 20 years of experience in the life insurance industry. He helps families understand their options, protect their income, and prepare for the unexpected with clear, straightforward guidance they can feel confident about.
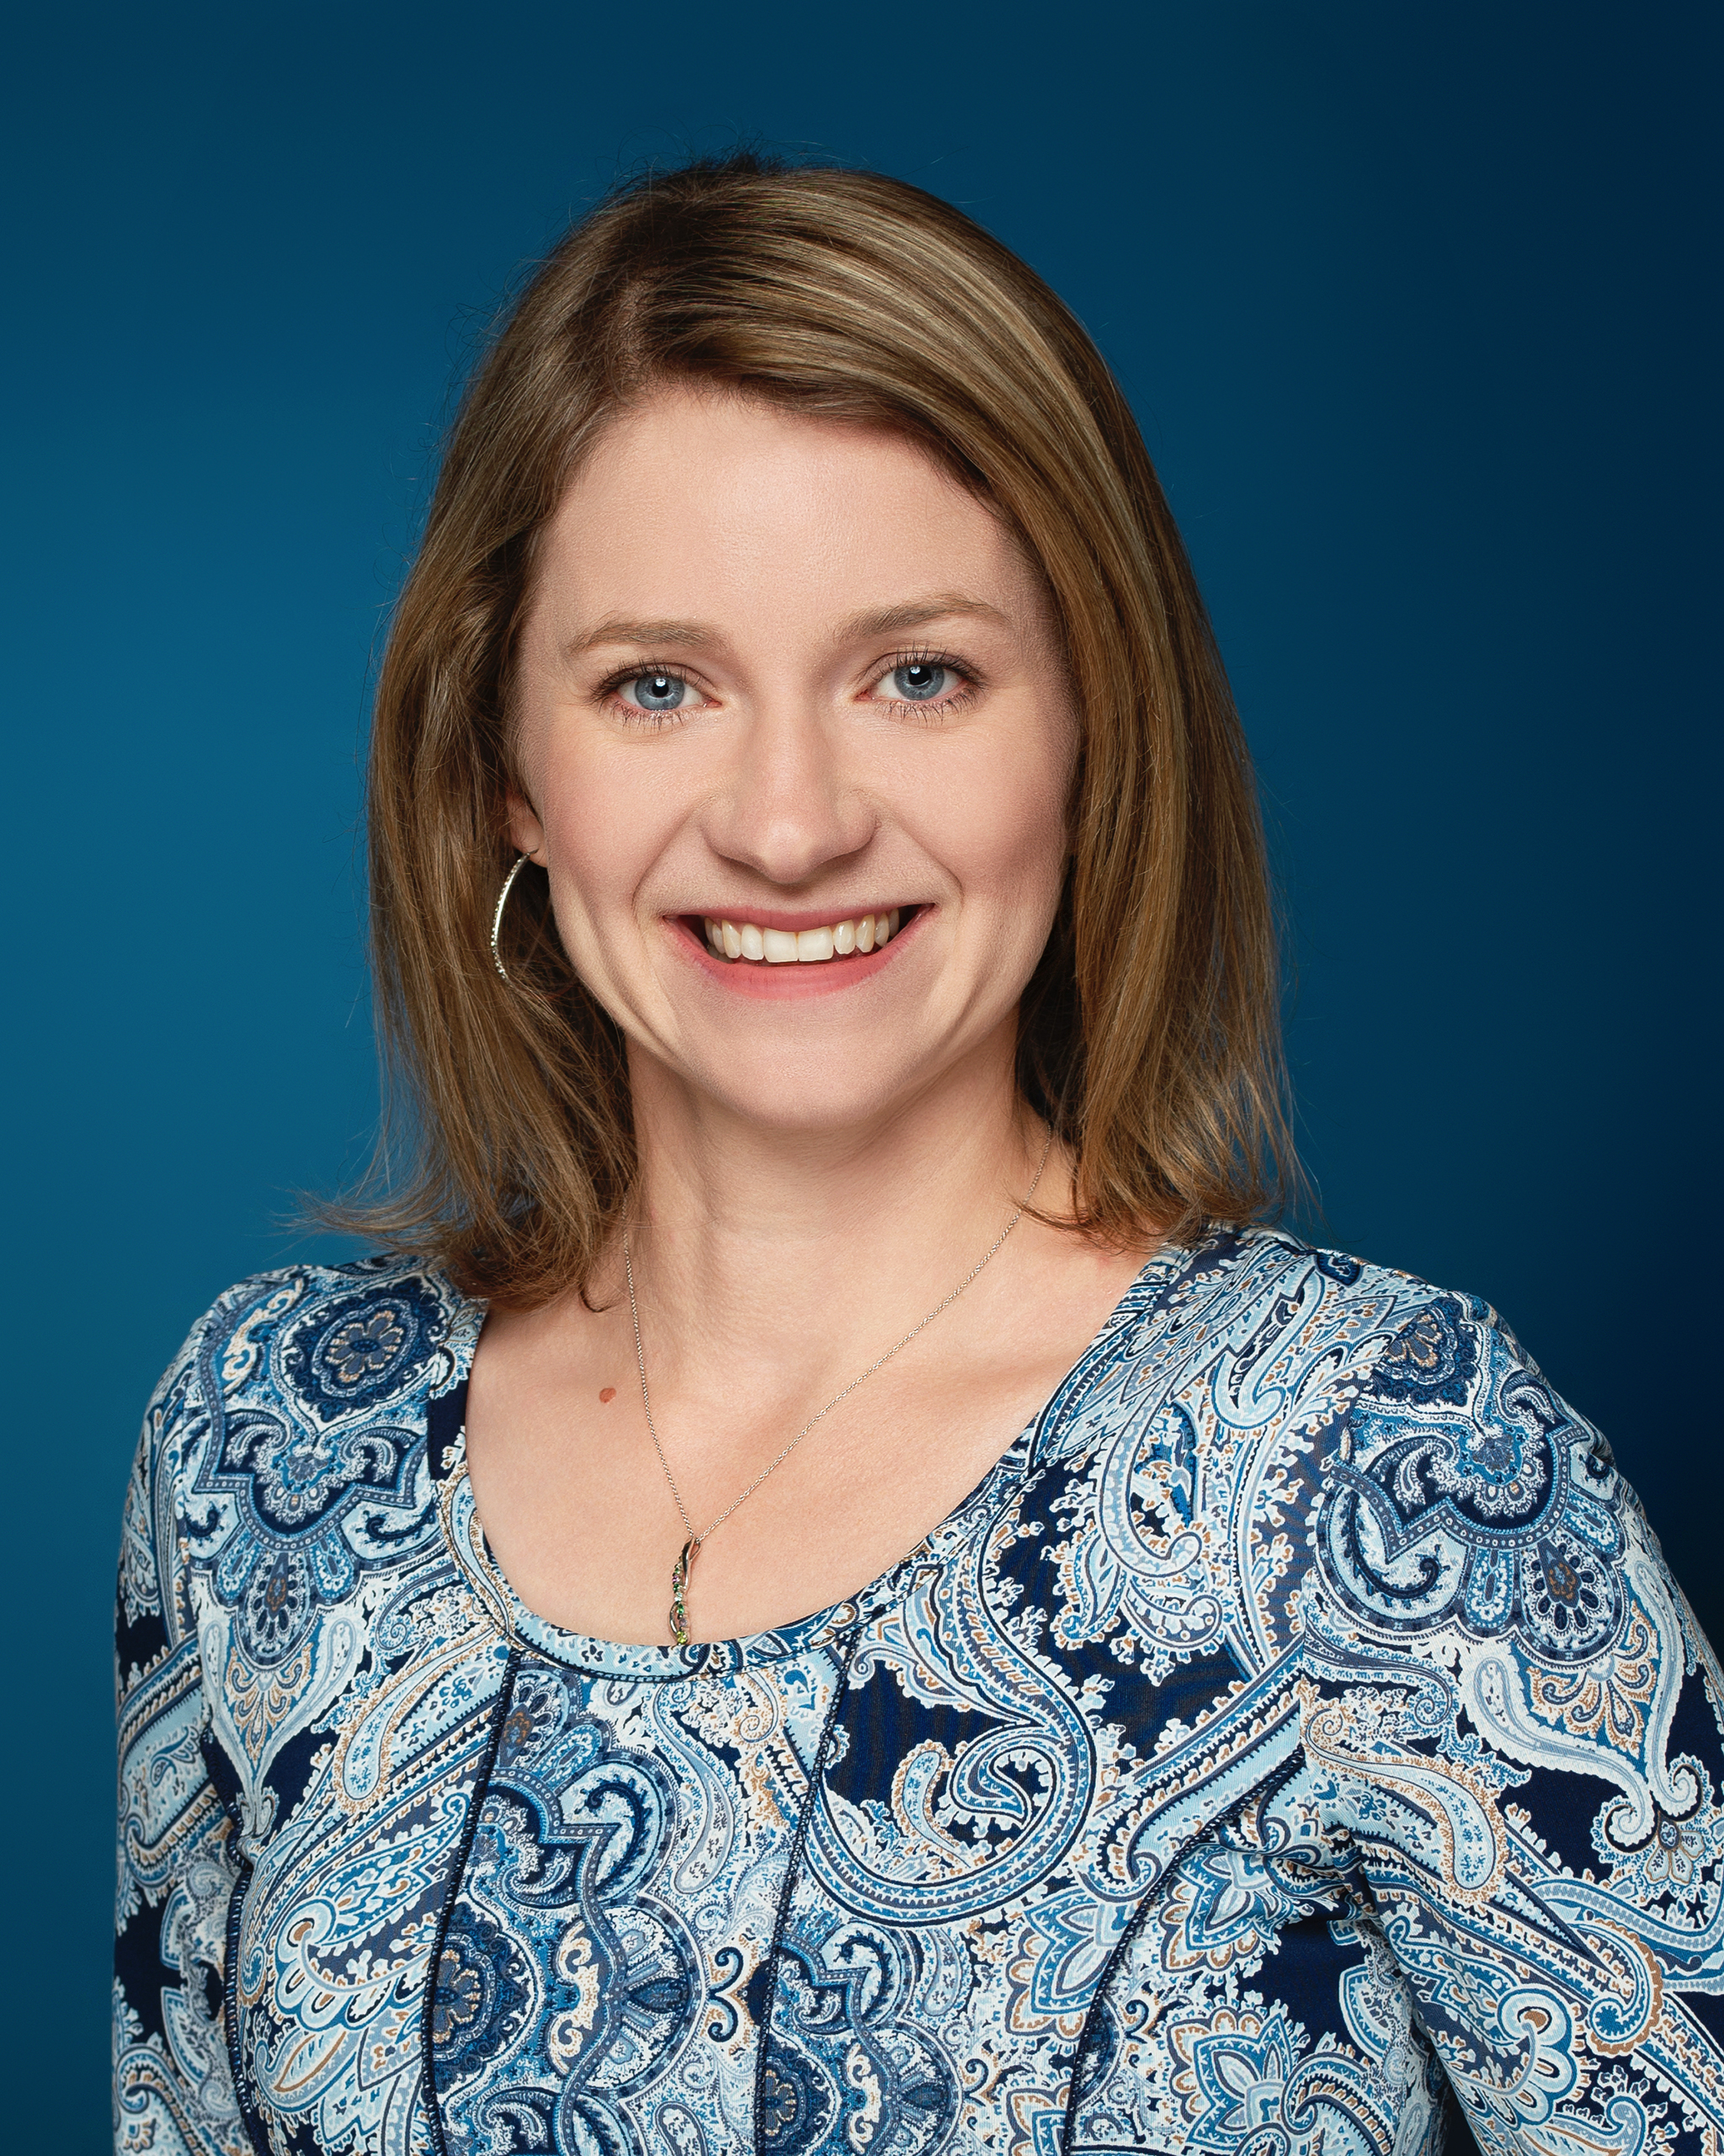
Melissa Coleman
Licensed Insurance Professional
Melissa has been a licensed insurance professional since 2012. She helps individuals and families understand their coverage options and make thoughtful decisions about protecting the people and priorities that matter most.
COMMON QUESTIONS
Questions About Protecting Your Business?
Business protection can involve ownership, key people, financial obligations, and long-term plans. Here are a few questions business owners often ask before scheduling a review.
What does business protection with life insurance actually do?
Life insurance can provide funds if an insured owner or key person dies. Depending on how the coverage is structured, those funds may help the business manage debt, operating expenses, the loss of a key person, or an ownership transition.
What is key person insurance?
Key person insurance is life insurance intended to help protect a business from the financial impact of losing someone whose leadership, skills, relationships, or production are important to the company. The business is commonly the policy owner and beneficiary when coverage is structured for this purpose.
Can life insurance help fund a buy-sell agreement?
Yes. Life insurance may be used to help provide funding for an ownership transfer after an owner dies when it is coordinated with a properly structured buy-sell agreement. The agreement itself should be prepared or reviewed by qualified legal professionals.
Is business protection only for companies with multiple owners?
No. A business with one owner may still have debts, employees, family members, or other financial responsibilities that could be affected by the owner’s death. Businesses may also depend heavily on key employees who are not owners.
How much business life insurance should we have?
There is no single amount that fits every business. We look at factors such as the financial impact of losing an owner or key person, business debt, operating needs, ownership arrangements, existing coverage, and the goals the business wants to protect.
Who should own the policy and receive the benefit?
That depends on the purpose of the coverage and how the strategy is structured. The business, an individual owner, or another appropriate party may own the policy or receive the benefit. We help explain the insurance considerations, while legal and tax professionals should advise on ownership agreements and individualized tax or legal matters.
Do I need an attorney or CPA involved?
For straightforward insurance planning, we can help you understand and compare coverage options. When the strategy involves ownership agreements, buy-sell planning, business entities, or tax considerations, it is important to coordinate with qualified legal and tax professionals.
What happens during the first conversation?
We start by learning how the business is structured, who it depends on, what financial obligations exist, what coverage is already in place, and what you want to protect. From there, we can determine which insurance strategies may be worth reviewing.
READY WHEN YOU ARE
Review Your Business Protection Options With PFG
A short conversation can help you understand how life insurance may support key person protection, business continuity, ownership planning, and other financial responsibilities tied to your business.
Clear information. Personal guidance. No pressure to make an immediate decision.
PFG LIFE LLC
Independent guidance for life insurance, family protection, and retirement income strategies.
Contact
Phone: 208-417-7295
Email: [email protected]
Insurance products are subject to eligibility and underwriting. Product availability varies by state. Guarantees are backed by the claims-paying ability of the issuing insurance company. Information provided is for educational purposes and is not individualized tax or legal advice. Consult a qualified tax or legal professional regarding your individual circumstances.
© 2026 PFG LIFE LLC. All rights reserved.