IUL & LIVING BENEFITS
Life Insurance Protection With More Flexibility for the Future
Indexed universal life insurance is designed to provide life insurance protection while also offering features that may support longer-term financial goals.
PFG helps you understand how IUL works, including potential cash value growth, policy costs, living benefit options, and the tradeoffs to consider before deciding whether it may fit your situation.
IIndependent guidance • Multiple-company access • No-pressure conversation
IUL is life insurance and is not a direct investment in the stock market. Policy features, cash values, living benefits, eligibility, charges, and availability vary by product, insurer, and state.
PROTECTION WITH LONG-TERM FLEXIBILITY
IUL Combines Life Insurance Protection With Cash Value Potential
Indexed universal life is a form of permanent life insurance. Like other life insurance, its primary purpose is to provide a death benefit to beneficiaries.
It can also build cash value over time. Interest credited to the policy may be linked to the performance of a market index, subject to the policy’s terms, caps, participation rates, floors, charges, and other limitations.
Because every policy works differently, it is important to understand both the potential benefits and the costs before deciding whether IUL fits your goals.
Life Insurance Protection
Provides a death benefit designed to help protect the people and financial responsibilities that matter to you, subject to eligibility requirements, underwriting, and policy terms.
Cash Value Potential
A portion of premium may support policy cash value. Crediting may be linked to an index, but the policy is not a direct investment in the market and policy charges affect values.
Living Benefit Options
Some policies offer riders that may allow access to a portion of the death benefit after certain qualifying events. Availability, qualifications, and effects on policy values vary.
IUL, EXPLAINED SIMPLY
An IUL Policy Should Fit Your Protection Goals—not Just a Projection
Indexed universal life insurance combines permanent life insurance protection with a cash value component. Premiums, policy charges, credited interest, and the amount of insurance all affect how the policy may perform over time.
Interest may be credited based in part on the performance of a market index, subject to the policy’s crediting method and limitations. The policy does not directly invest your money in the index.
IUL can offer flexibility, but it also requires ongoing funding and monitoring. Changes in premiums, policy charges, credited interest, withdrawals, or loans can affect cash value and the death benefit.
PFG helps you review the policy mechanics, costs, assumptions, and available features so you can decide whether an IUL strategy is appropriate for your needs.
Important to Know
IUL policies vary by insurer and state. Caps, participation rates, floors, charges, surrender periods, loan provisions, riders, and other terms vary by policy and may change as permitted by the contract.
Policy loans and withdrawals may reduce cash value and the death benefit and may cause the policy to lapse if not properly managed. Living benefits are subject to rider terms, qualifying events, and policy eligibility.
WHAT WE REVIEW TOGETHER
An IUL Review Starts With More Than One Number
An illustration can help explain how a policy may work, but it is only part of the picture. We look at your protection needs, funding expectations, policy features, and priorities together before discussing what may be appropriate.
Your Protection Needs
We start with who and what you want to protect, including income needs, debts, family responsibilities, business obligations, and legacy goals.
Your Funding Plan
We discuss how much premium you are comfortable maintaining and how funding levels may affect policy values, costs, and long-term performance.
Policy Features and Costs
We review crediting options, policy charges, caps, participation rates, floors, surrender provisions, and other features that may affect the policy over time.
Living Benefits and Access
We look at available riders, qualifying events, access to cash value, loans, withdrawals, and how those choices may affect the policy and death benefit.
A SIMPLE, PERSONAL PROCESS
Clear Guidance From IUL Review to Informed Decision
We start with your protection needs, goals, budget, and current coverage. Then we help you review appropriate IUL options, understand how the policy works, and decide what makes sense for you.
1
Understand Your Situation
We review who and what you want to protect, your current coverage, financial priorities, budget, and longer-term goals.
2
Review Appropriate Options
We look at available IUL policies that may fit your needs, health, eligibility, funding expectations, and priorities.
3
Compare Policy Features
We explain the differences in policy costs, crediting methods, living benefits, access to cash value, and other important tradeoffs.
4
Make an Informed Decision
You decide what fits your situation. We’re here to answer questions and provide guidance—not pressure you into a policy.
A straightforward conversation to understand your needs and review appropriate options.
PERSONAL GUIDANCE
Work With People Who Take the Time to Understand Your Protection Goals
Life insurance decisions are personal. We begin by understanding who you want to protect, your current coverage, financial priorities, budget, and longer-term goals before discussing possible solutions.
As an independent life insurance brokerage, PFG can help you review appropriate IUL and living benefit options rather than assuming one policy or approach is right for everyone.
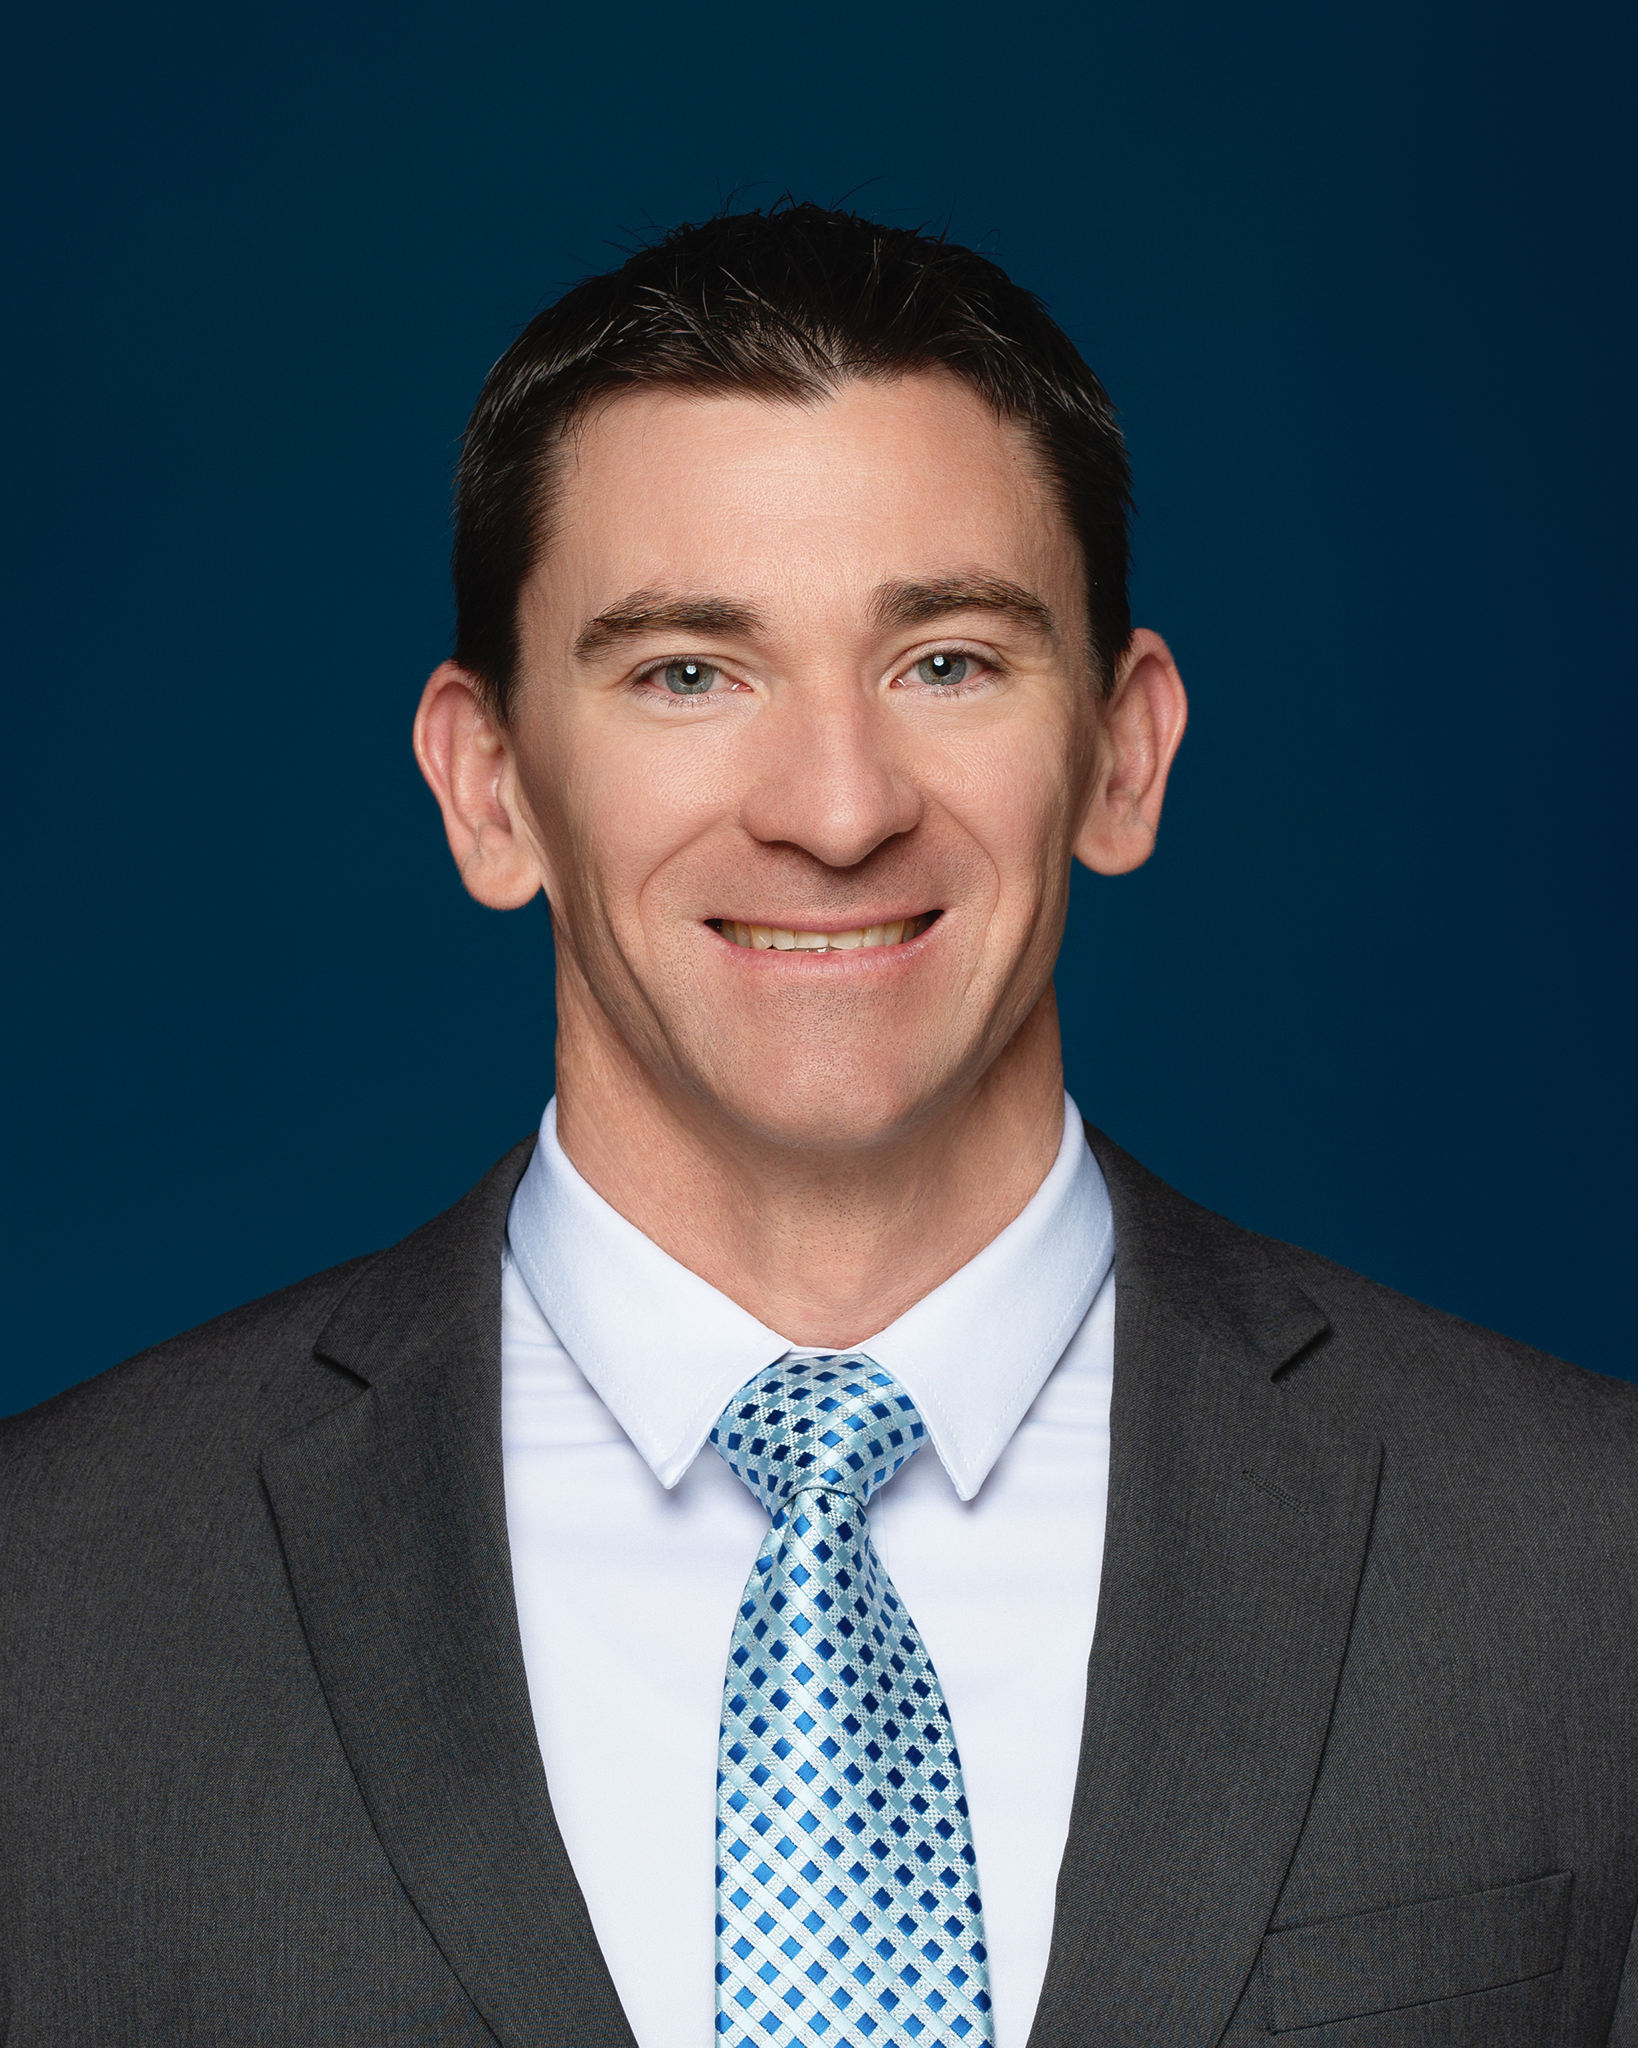
G. Aaron Coleman
Founder, Productive Financial Group
Aaron brings more than 20 years of experience in the life insurance industry. He helps families understand their options, protect their income, and prepare for the unexpected with clear, straightforward guidance they can feel confident about.
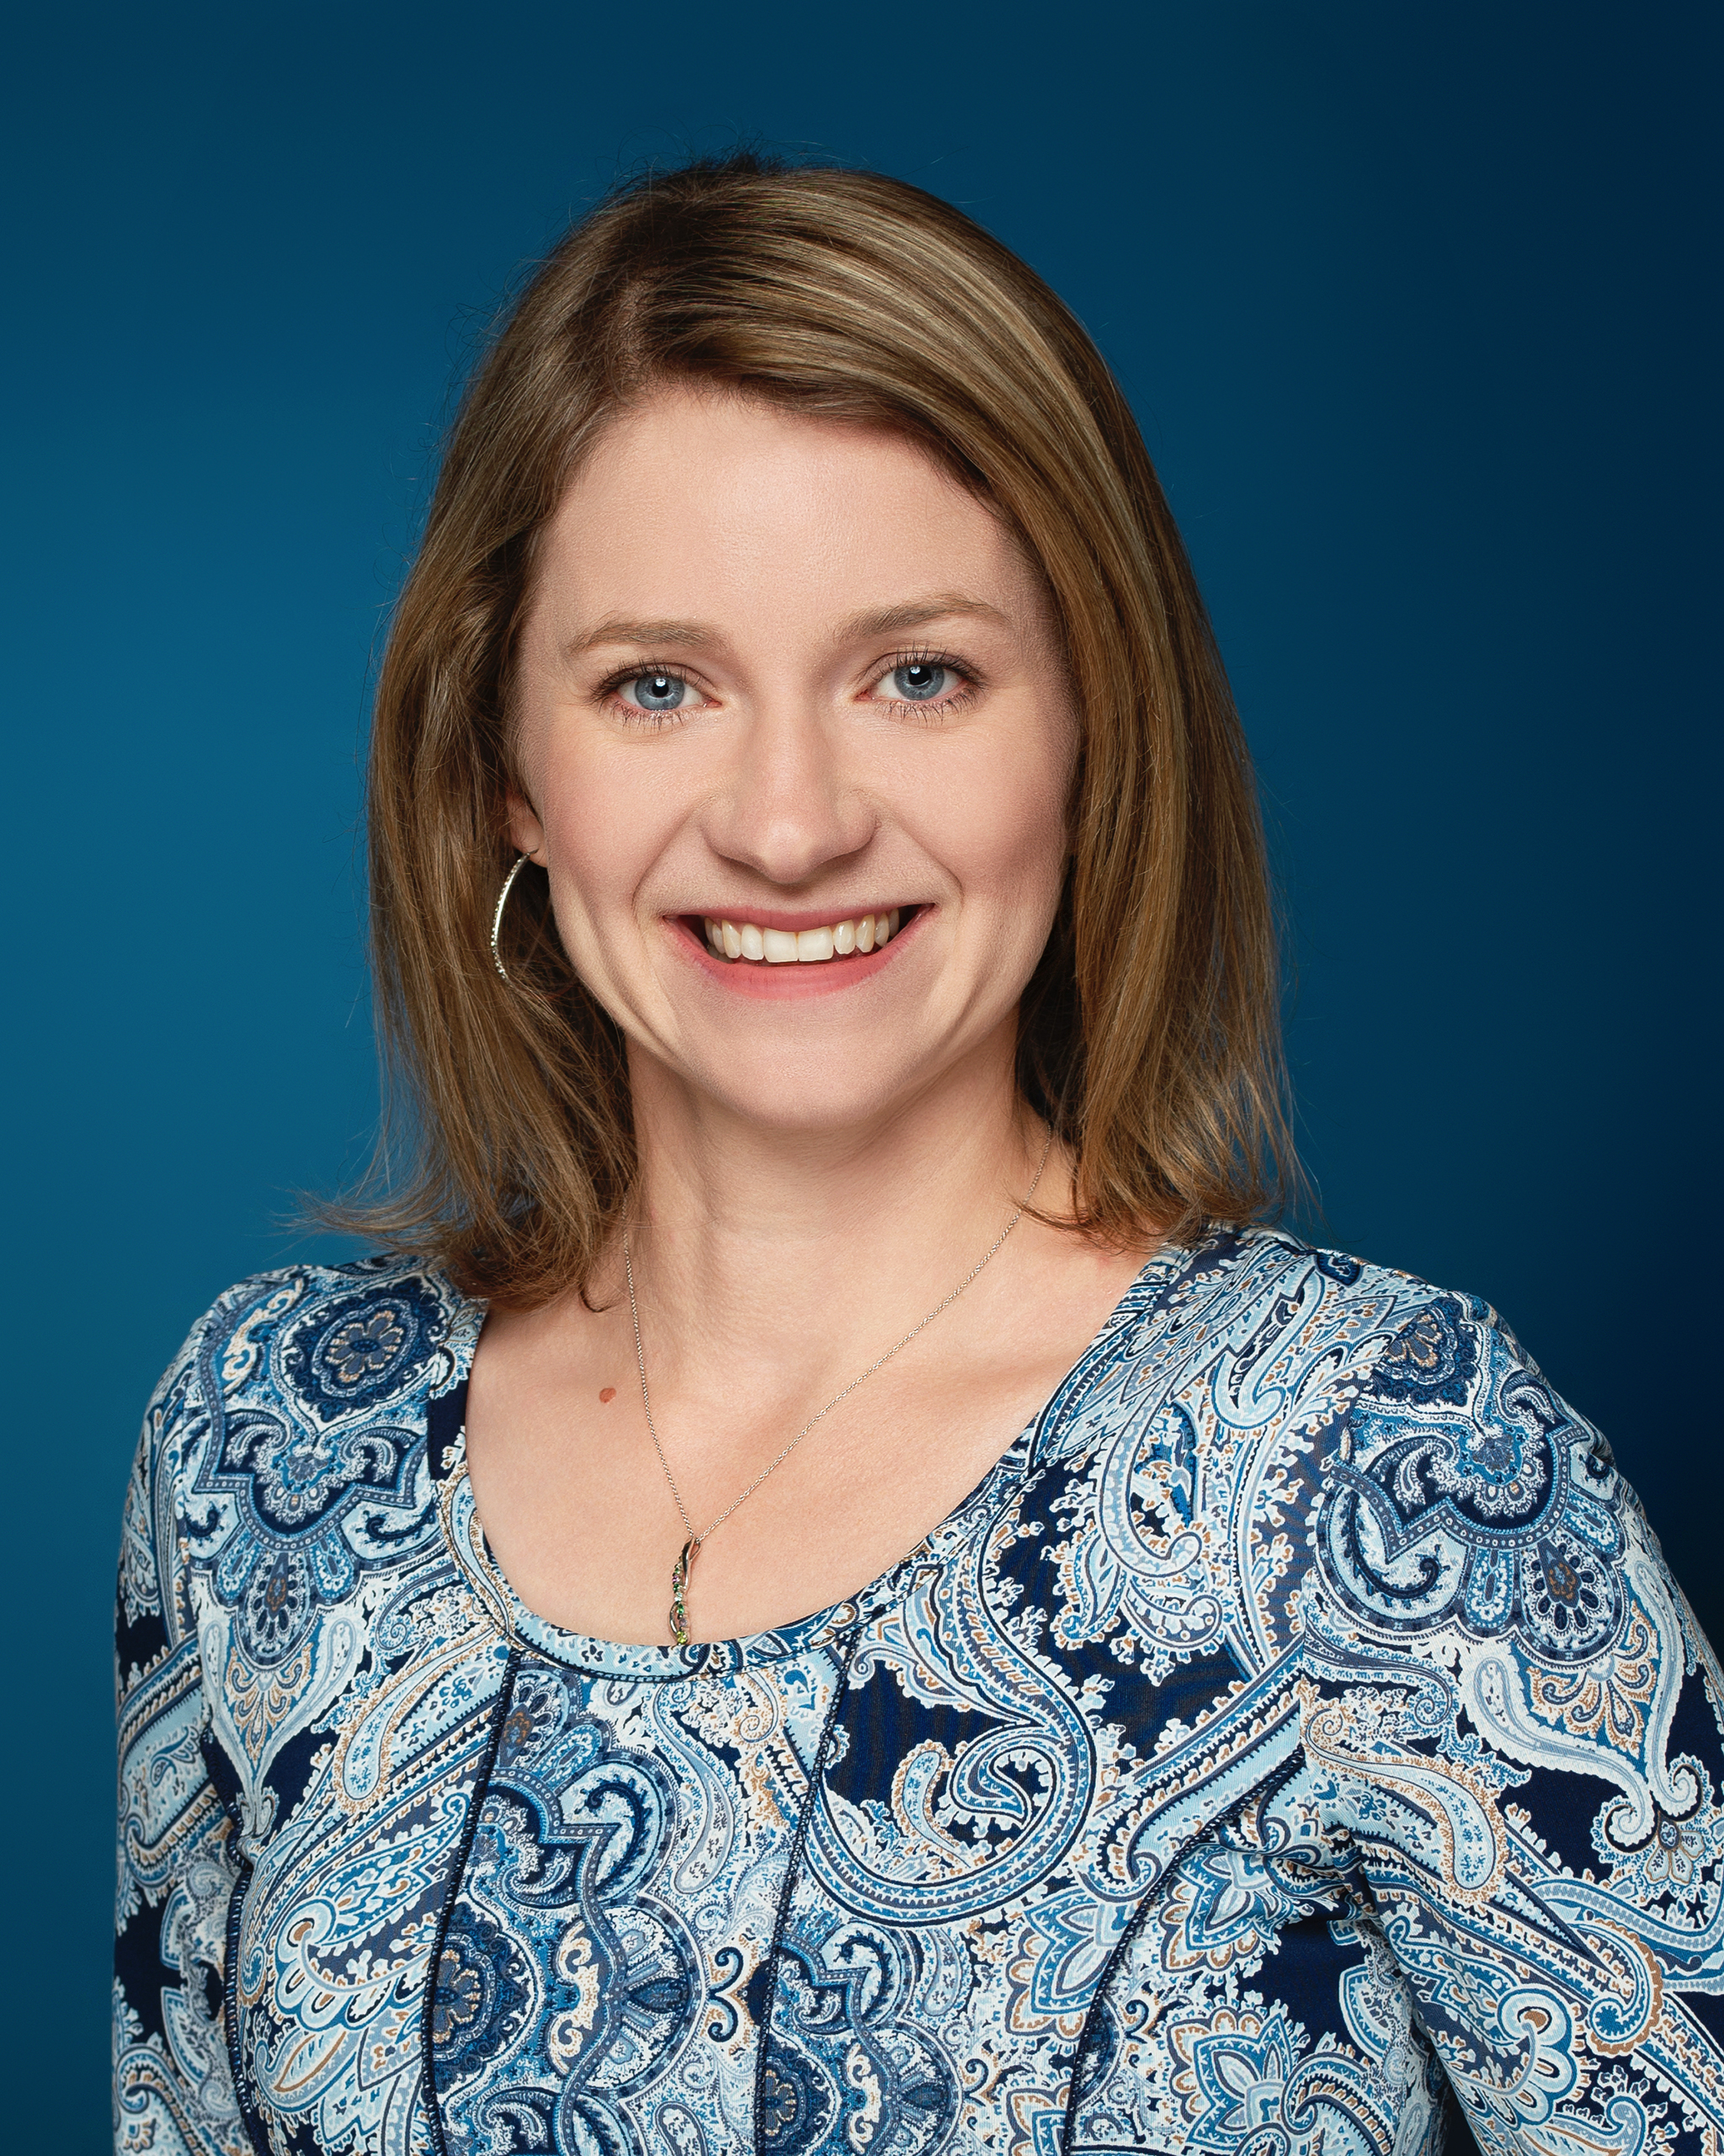
Melissa Coleman
Licensed Insurance Professional
Melissa has been a licensed insurance professional since 2012. She helps individuals and families understand their coverage options and make thoughtful decisions about protecting the people and priorities that matter most.
COMMON QUESTIONS
Questions About IUL & Living Benefits?
IUL policies can have a lot of moving parts. Here are a few common questions people often want answered before scheduling a review.
What is indexed universal life insurance?
Indexed universal life, or IUL, is permanent life insurance that provides a death benefit and can also build cash value over time. The policy’s interest crediting may be linked to a market index, but your money is not invested directly in the market.
Does an IUL invest my money directly in the stock market?
No. An IUL does not put your money directly into stocks or an index fund. Instead, the insurance company uses an index as part of the formula for determining how interest may be credited to the policy.
What are living benefits?
Living benefits may allow you to access part of a policy’s death benefit while you are still living if certain qualifying events occur. The specific benefits, qualifications, and availability depend on the policy and rider.
Is cash value growth guaranteed?
Not all cash value growth is guaranteed. How a policy performs can depend on how it is funded, policy costs, credited interest, and how the policy is used over time. That is why we review both the guarantees and the assumptions before you make a decision.
Can I access the policy’s cash value?
In many policies, cash value may be accessed through loans or withdrawals. Those choices can affect the policy’s cash value and death benefit, so we help you understand how access works before relying on it as part of your plan.
How much should I contribute to an IUL policy?
There is no one amount that is right for everyone. We look at your protection needs, budget, goals, and how long you expect to maintain the policy before discussing a funding approach that may make sense.
Will I be pressured to buy anything?
No. The goal of the review is to help you understand your options, ask questions, and decide whether an IUL strategy fits your situation. You do not have to make a decision during the first conversation.
What happens during the first conversation?
We start by learning about who you want to protect, your current coverage, budget, priorities, health considerations, and longer-term goals. Then we can review appropriate options, explain how they work, and answer your questions clearly.
READY WHEN YOU ARE
Review Your IUL & Living Benefits Options With PFG
A short conversation can help you understand how IUL protection, cash value features, living benefits, costs, and funding expectations may fit your goals.
Clear information. Personal guidance. No pressure to make an immediate decision.
PFG LIFE LLC
Independent guidance for life insurance, family protection, and retirement income strategies.
Contact
Phone: 208-417-7295
Email: [email protected]
Insurance products are subject to eligibility and underwriting. Product availability varies by state. Guarantees are backed by the claims-paying ability of the issuing insurance company. Information provided is for educational purposes and is not individualized tax or legal advice. Consult a qualified tax or legal professional regarding your individual circumstances.
© 2026 PFG LIFE LLC. All rights reserved.